BrightWay Credit Card Mobile
OneMain Financial
- 4.6
- 6.79K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
BrightWay Credit Card Mobile Pros and Cons
Pros
- Quick access to balances, transactions, payments, and account details.
- Payment reminders can help reduce the risk of missing monthly due dates.
- Mobile access makes managing the card convenient while traveling or shopping.
- Transaction alerts can help users notice unfamiliar activity sooner.
- Useful for monitoring available credit between billing statements.
Cons
- Some features may require a stable internet connection to work properly.
- App availability and features can vary depending on the cardholder’s account.
- Users may need to contact support for disputes or complex account issues.
- Frequent notifications may feel excessive unless alert settings are customized.
- A mobile app cannot replace careful budgeting and responsible credit use.
 Analysis by All-app
Managing a credit card from a phone can be convenient, but finance apps deserve a more careful look than a typical shopping or entertainment app. I spent time examining BrightWay Credit Card Mobile as a practical account-management tool, paying particular attention to what it lets a cardholder control, where sensitive information enters the experience, and how much confidence the app inspires without making assumptions beyond what is visible. My overall impression is that it is a focused companion for people who already use the BrightWay Credit Card and want everyday access to spending, payments, and rewards.
The app is developed by OneMain Financial and is available free of charge for Android users running version 6.0 or later. It is rated for Everyone, which describes its general audience rather than removing the need for sensible care around financial credentials. The application first appeared on August 16, 2021, and the current version is 5.9.0. Those details matter because an account app should feel maintained and compatible with a reasonably broad range of devices, while users should still keep their operating system and app installation current.
BrightWay Credit Card Mobile has built a visible audience, with an average rating of 4.6 from around fifteen thousand ratings and more than five hundred thousand installs. I would treat that as useful context rather than a guarantee. A high rating can indicate that the main tasks work well for many people, but it does not tell me whether the app suits every financial situation. The more important question is whether its everyday controls are clear enough to help a cardholder act deliberately instead of simply checking a balance and moving on.
What I could verify about control and trust
The central purpose is straightforward: manage spending, payments, and rewards connected with the BrightWay Credit Card. That focus is reassuring in one sense. It is not presented as a general budgeting platform, investment service, or broad financial dashboard. I would approach it as a dedicated card companion, which usually makes the intended workflow easier to understand than an app trying to cover every part of personal finance.
In practical use, the first thing I would want from an app like this is a quick way to understand my current position before making another purchase. A balance view can help answer whether a planned expense is sensible, while a payment area should make it easier to act before a due date. Rewards add a second reason to open the app, since users may want to check whether their card activity is producing benefits. The value is not in any single screen; it is in having these related tasks in one place.
I also like the idea of separating observation from action. Checking recent spending is a low-risk activity, while submitting a payment is consequential. A well-designed card app should make that distinction visible through its wording and confirmation steps. When I review an account tool, I look for whether I can pause and verify the amount, account, and timing before committing. That habit is particularly important on a small phone screen, where a rushed tap can be harder to notice than on a desktop banking site.
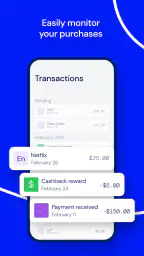
One useful workflow is to open the app before a larger purchase, review recent activity, and then decide whether the expense belongs in the current payment plan. This is more helpful than waiting for a monthly statement to reveal a problem. It can also expose an unfamiliar transaction sooner, giving the cardholder a reason to investigate through the appropriate account-support channel rather than ignoring it.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The app’s identity matters here. Because BrightWay Credit Card Mobile comes from OneMain Financial, I would prefer using it for BrightWay account tasks over entering card details into an unrelated budgeting app simply to see a balance. That does not make every digital risk disappear, but it reduces the number of services involved in a basic account check. For a user who wants a narrow tool rather than a financial ecosystem, that is a reasonable advantage.
Controls are most useful when used as a routine
I would not wait until a payment is urgent to learn the layout. My recommendation is to sign in during a calm moment, inspect the spending and payment areas, and understand which screens are informational and which begin an account action. This small preparation can prevent mistakes later, especially when the user is travelling, shopping, or dealing with an unexpected expense.
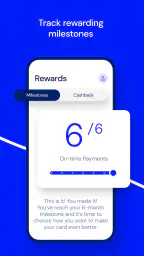
A second practical habit is to treat rewards as a review point rather than a reason to spend. Seeing rewards in the same app as card activity can make benefits easier to remember, but it can also encourage unnecessary purchases if the user focuses on earning instead of affordability. I would use the rewards view to understand what has accumulated, then return to the spending picture before deciding whether the card remains the right payment method.
The app is also more useful when paired with personal records. I would not rely on a mobile balance alone for a long-term financial plan. Instead, I would use the app for current account visibility and keep a separate household budget for rent, utilities, subscriptions, and other obligations. This division gives BrightWay Credit Card Mobile a clear job without asking it to replace a full budgeting system.
That trade-off is important. A dedicated card app can be quicker than a general finance application because it avoids unrelated categories and accounts. On the other hand, it may not offer the cross-account picture that someone needs to compare several cards, bank accounts, loans, and cash expenses. If your main goal is debt planning across multiple lenders, a broader financial tool may be more suitable, provided you are comfortable with its account-linking and data-sharing choices.
Where sensitive information enters the experience
Any credit-card application involves moments that deserve extra attention: signing in, reviewing transactions, arranging a payment, and handling account-related support. I would avoid performing those tasks on a public or shared device, and I would be cautious with unexpected messages that ask me to open a link or disclose credentials. The safest workflow is to open the installed app directly and verify the context before entering information.
I also recommend checking the app’s permission prompts and privacy explanations on your own device before granting access. I would not assume that a finance app needs every permission a phone can offer. If a request appears unrelated to checking the account, making a payment, or viewing rewards, I would pause and look for an explanation rather than approving it automatically. This is a general security practice, but it is especially relevant when the app is connected to credit activity.
There is a difference between what an app visibly allows and what a user may imagine it does. BrightWay Credit Card Mobile is clearly centered on card management, but I would not treat it as a complete identity-protection service, a credit-counselling program, or a substitute for reviewing official account communications. The app can be part of a responsible routine; it should not become the only place where a user checks important financial information.
Data-sensitive moments also include the ordinary act of looking over a screen. If I check a balance or transaction list in a crowded place, someone nearby may see information that I would rather keep private. A phone’s lock screen, notification previews, and recent-apps view can expose more than expected. I would review those device settings and avoid leaving the app open when handing the phone to another person.
Another underappreciated risk is confusion between a pending transaction and a completed one. Card activity can change as merchants finalize charges, so I would avoid treating a single glance as a permanent account statement. If a purchase looks unfamiliar or an amount does not match my receipt, I would record the details and follow the account’s official process instead of repeatedly refreshing and guessing.
User agency matters more than visual polish
For me, trust in a finance app comes from being able to make informed choices. Before confirming a payment, I want enough context to know what I am submitting and when it will affect my account. Before relying on a rewards figure, I want to understand that rewards are connected to card activity and may not be the same thing as available cash. The app’s usefulness depends on whether it helps me distinguish those concepts rather than blending them together.
A realistic example is a user who receives a paycheck near the end of the week and has several card purchases already posted. I would open the app, review the recent spending, check the payment area, and compare the proposed payment with money reserved for essentials. If the amount is affordable, I could proceed after checking the final details. If it is not, the app has still served a valuable purpose by making the pressure visible before I submit an unrealistic payment.
That scenario also shows why a quick payment button is not automatically a complete solution. Convenience can shorten the distance between seeing a balance and sending money, but it can also encourage impulsive decisions. I prefer a workflow that treats the payment as a deliberate choice. Users should read every confirmation screen, especially when using a small display or switching between accounts.
I would also keep notifications purposeful. Alerts can help a person remember to inspect activity, but too many notifications may become background noise. If the app offers notification choices on your device or within the account experience, I would select only those that genuinely support my routine. A notification should prompt a useful check, not replace one.
People sharing a household may need to discuss who is allowed to use the phone or view account information. A card app can make access easier for the primary user, but convenience should not be confused with permission for everyone nearby. I would keep sign-in details private and avoid saving sensitive information in places another person can casually access.
Who will benefit and who should look elsewhere
BrightWay Credit Card Mobile is a good fit for an existing BrightWay cardholder who wants a direct way to monitor spending, arrange payments, and keep an eye on rewards. It is especially practical for someone who prefers checking an account during the day rather than waiting for a computer. The focused purpose should also appeal to users who do not want a complicated financial dashboard filled with unrelated products.
I would be more cautious about recommending it to someone looking for a complete household-finance system. If you need detailed category budgets, investment tracking, shared planning, or a consolidated picture across many institutions, a dedicated card app may feel narrow. A general finance application or a spreadsheet could be better for that job, even though those alternatives introduce their own setup and privacy considerations.
It may also be the wrong choice for a person who does not have a BrightWay Credit Card or who expects a mobile app to replace customer support. Account management can be convenient, but complicated disputes, identity questions, and unusual payment situations may still require direct assistance. I would use the app to gather the relevant account information first, then choose the appropriate support route rather than expecting every issue to be solved inside the mobile interface.
Users with older phones should pay attention to compatibility. The app requires Android 6.0 or later, so a device below that threshold would not be a suitable platform. For supported devices, keeping the operating system updated is still sensible, particularly when handling financial information. I would also avoid installing the app on a phone that no longer receives security updates, even if it technically meets the minimum requirement.
My cautious verdict after weighing convenience and control
I see BrightWay Credit Card Mobile as a useful, focused finance app rather than a complete answer to personal money management. Its strongest quality is concentration: spending, payments, and rewards belong together for a BrightWay cardholder, and the app gives those tasks a mobile home. The free price removes a barrier to trying it, while its broad audience and established install base suggest that it is intended for ordinary day-to-day access.
My recommendation comes with a clear condition: use it actively, not passively. Check transactions regularly, pause before submitting payments, treat rewards as information rather than spending motivation, and review device privacy settings. Those habits give the app a better chance of supporting good decisions. They also prevent a convenient account screen from becoming a substitute for a real budget or careful account review.
The main limitation is scope. Someone wanting a unified view of several financial providers may outgrow it quickly, and someone facing a complicated account problem may still need help beyond the app. In those cases, a broader budgeting tool or direct support may be the better complement. I would not choose a general-purpose alternative solely because it has more screens; I would choose it only if I genuinely needed the additional financial picture.
For the right user, BrightWay Credit Card Mobile is a sensible way to stay close to a BrightWay account without adding unnecessary complexity. I would recommend it to a cardholder who values quick visibility and is willing to review each action carefully. I would skip it as a primary financial-planning tool, but as a controlled mobile companion for spending, payments, and rewards, it earns a cautious recommendation.
Frequently Asked Questions
What is BrightWay Credit Card Mobile used for?
BrightWay Credit Card Mobile is designed to help cardholders manage their BrightWay credit card account from an Android or iOS device. After signing in, users can typically review their balance, available credit, recent transactions, payment due date, minimum payment, and account notices. The app is mainly a convenient account-management tool rather than a separate banking service.
Can I make a payment through the BrightWay Credit Card Mobile app?
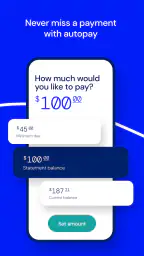
Yes, the app is intended to let eligible cardholders make payments directly from their mobile device. Before submitting a payment, check the selected bank account, payment amount, and processing date carefully. Payment availability and posting times may vary, and users should not assume that a payment made near the due date will be credited immediately. Always keep confirmation details for your records.
Is BrightWay Credit Card Mobile safe to use?
The app generally uses account sign-in and security protections intended to help safeguard personal and financial information. However, mobile security also depends on the user. Download the application only from an official app store, avoid signing in over unsecured public networks, use a strong unique password, and enable device security such as a passcode, fingerprint, or facial recognition when available.
What information do I need to access my BrightWay account?
You will normally need your BrightWay account credentials, and the service may request additional verification during sign-in or registration. New users should follow the setup instructions shown in the app and provide only information requested through official screens. If you forget your login details or your account becomes locked, use the in-app recovery options or contact BrightWay customer support.
Are there any limitations or fees when using BrightWay Credit Card Mobile?
Downloading and using the app may not involve a separate application fee, but normal card-account charges, interest, late fees, or other terms still apply according to your credit agreement. Your mobile carrier may also charge data fees. Some features can depend on account eligibility, maintenance, internet access, or app updates, so review the cardholder agreement and current in-app disclosures before relying on a feature.